The Debt Collection Process: A Step-by-Step Guide for BFSI Teams
A walkthrough of the debt collection process for Indian BFSI lenders: early warning checks, SMA/NPA staging, recovery agent rules, SARFAESI, and DRT.
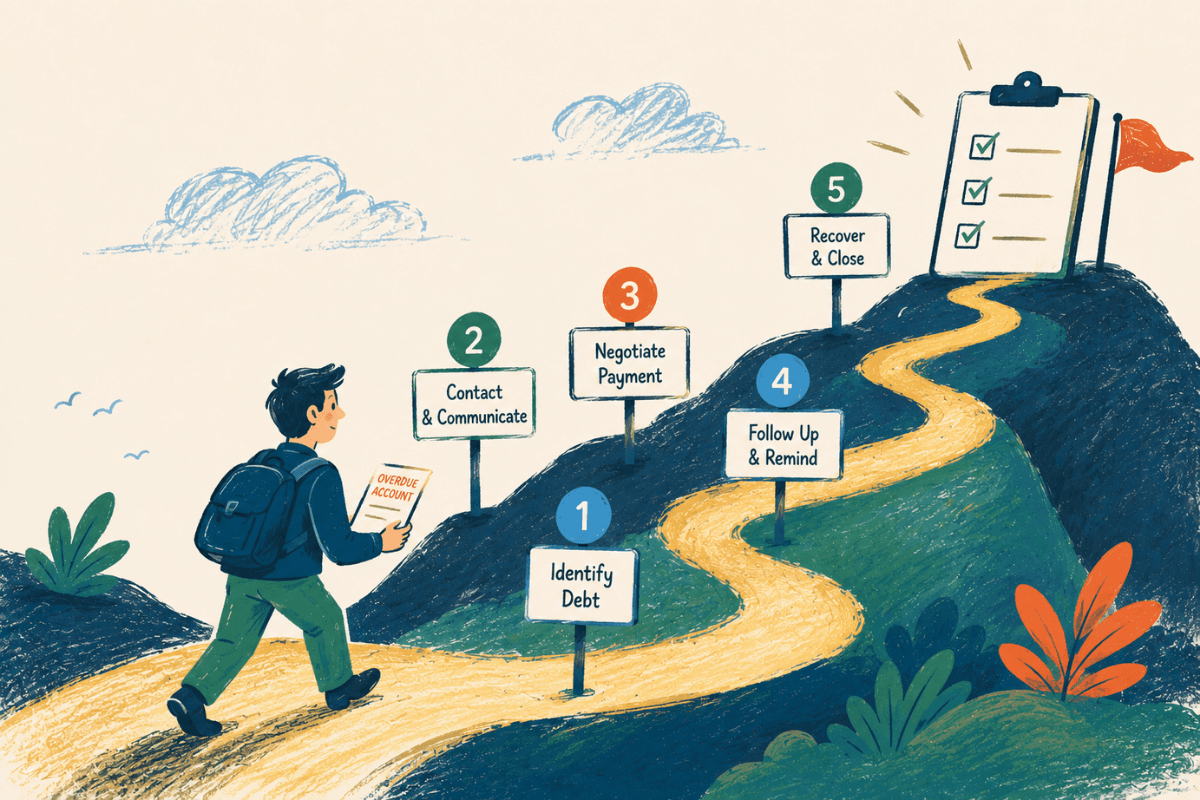
The debt collection process is the step-by-step workflow lenders use to recover overdue loans under Reserve Bank of India rules. The cycle moves through seven distinct stages: early warning checks, early arrears contact, SMA and NPA loan classification, recovery agent outreach, loan write-offs, SARFAESI asset actions, and Debt Recovery Tribunal claims. Each step sets clear contact rules, time limits, and lender duties.
Detect Credit Risk Before Missing an EMI
Lenders track early warning signals to spot borrower stress before a payment fails. Continuous account checks help credit teams see cash flow pressure early across retail and business accounts.
Research on credit risk management by IDfy[1] points out several key warning signs. These include a borrower cutting back auto-debit mandates or running low balances before an EMI date. They also include new loan inquiries with other lenders, or falling GST filings for commercial borrowers. Catching these signs lets credit teams offer revised terms or friendly check-ins before an account falls into arrears.
Early risk checks are vital for Non-Banking Financial Companies (NBFCs) and fintech lenders. Unlike legacy commercial banks, non-bank lenders lack branch networks or long deposit histories. Using automated risk triggers during ongoing monitoring helps lenders isolate high-risk accounts quickly.
Organize Early Delinquency Outreach in the First 30 Days
Early outreach relies on digital contact and high self-cure rates during the first month. When a borrower misses a due date, lenders trigger structured contact workflows.
Industry findings from Frenzo Finserv recovery research[2] show that fast outreach directly aids collections. Their data estimates an 80% recovery rate when contact starts within the first 7 days of default. This rate drops to about 60% between days 30 and 60. It falls below 40% once an account becomes an NPA.
| Overdue Window | Estimated Recovery Rate | Typical Communication Cadence |
|---|---|---|
| First 7 days after missed EMI | ~80% | Automated WhatsApp/SMS nudges (days 1-5), outbound call attempts (days 6-7) |
| 30-60 days past due (SMA-1) | ~60% | AI risk segmentation routes higher-risk accounts to human agents; restructuring offers or field visits in final days of 30-day window |
| 90+ days past due (NPA) | Below 40% | Case escalates beyond early delinquency operations |
Teams managing early arrears often adopt a collections intelligence solution to coordinate digital outreach across channels.
Classify Past-Due Accounts Under SMA and NPA Rules
Lenders run loan grading during daily day-end system batches to track overdue balances. While internal teams reach out to borrowers, banking rules mandate strict balance sheet reserves.
Under Reserve Bank rules explained in HDB Financial Services compliance guides[3], past-due loans enter Special Mention Account (SMA) stages right away:
- SMA-0: Overdue balance from 1 to 30 days
- SMA-1: Overdue balance from 31 to 60 days
- SMA-2: Overdue balance from 61 to 90 days
If a loan stays unpaid past 90 days, it becomes a Non-Performing Asset (NPA). For overdraft accounts, loans turn into NPAs when balances exceed sanctioned credit limits for 90 straight days. Under Reserve Bank rules documented on TaxGuru regulatory archives[4], lenders must update this loan staging during daily day-end batch runs.
| Asset Stage | Delinquency Period | Mandatory Provisioning Requirement |
|---|---|---|
| Sub-Standard | NPA for 12 months or less | 15% of total balance |
| Doubtful | NPA over 12 months (D1, D2, D3 tiers) | Higher percentage based on secured collateral |
| Loss Asset | Identified as uncollectible by auditors or inspectors | 100% provision or balance sheet write-off |
Internal days-past-due buckets run alongside these regulatory stages. But operational buckets guide daily outreach, while SMA and NPA rules set mandatory loan reserves.
Engage Recovery Agents Under RBI Conduct Rules
Lenders bear full legal liability for outside recovery agents and must enforce strict conduct limits. When internal outreach fails, lenders often assign overdue accounts to field agencies.
Under the Reserve Bank’s Fair Practices Code, lenders must not intimidate or harass borrowers. Rules hosted on TaxGuru regulatory archives[5] set clear boundaries for recovery staff:
- Contact Hours: Agents may only call or visit borrowers between 8:00 AM and 7:00 PM.
- Privacy Protections: Outreach is limited to the borrower and verified guarantors. Agents cannot contact family members, coworkers, or friends to demand repayment.
- Humiliation Bans: Lenders cannot post public notices, use social media, or send anonymous threats.
- Documentation Standards: Field agents must carry official identity cards and lender authorization letters with verified phone numbers.
- Call Recording: Lenders must record all inbound and outbound calls with borrowers.
In addition, agents must pass certificate tests run by the Indian Institute of Banking and Finance[6]. Under central bank outsourcing rules, lenders stay fully responsible for agency conduct. Using verified identity data through KYC document verification ensures that borrower records stay accurate during external agency handoffs.
Evaluate Loan Write-Off and Technical Write-Off Options
A loan write-off cleans the lender’s balance sheet without clearing the borrower’s debt. When an account cannot be recovered through routine channels, lenders consider an accounting write-off.
Commentary from Vinod Kothari Consultants on write-off procedures[7] confirms that a write-off is an internal accounting entry, not a debt waiver. The lender absorbs the bad debt against its loan reserves. But the borrower remains legally bound to repay every rupee owed.
Lenders often use technical write-offs to clean balance sheet ratios. In a technical write-off, the bad debt leaves head-office assets while local branch teams continue active recovery efforts. Any funds collected after this step are booked as other income for the bank.
Enforce Security Interests Under the SARFAESI Act
Secured lenders can take and sell pledged collateral without prior court approval once an account becomes an NPA. For home loans and secured business debt, the SARFAESI Act provides swift enforcement rights.
As outlined in TaxGuru’s overview of SARFAESI enforcement[8], the statutory action follows four key steps:
- Section 13(2) Demand Notice: The lender issues a formal notice demanding full repayment within 60 days. This notice is sent by registered post, courier, or digital delivery.
- Borrower Objections: The borrower can submit written objections during this 60-day window. The lender must review these objections and reply in writing if they reject them.
- Asset Possession under Section 13(4): If the borrower does not pay within 60 days, the lender can take physical possession of the pledged asset.
- Collateral Sale: The lender appoints an officer to appraise and auction the property to recover unpaid principal and legal costs.
Borrowers who dispute SARFAESI enforcement can file an appeal with the Debt Recovery Tribunal within 45 days of asset possession.
Escalate to the Debt Recovery Tribunal
Unsecured debts and unpaid loan shortfalls move to judicial recovery through Debt Recovery Tribunals. When collateral is lacking or falls short, lenders turn to these specialized courts.
Data from the Department of Financial Services[9] shows that India maintains 39 Debt Recovery Tribunals and 5 Appellate Tribunals. These specialized bodies hear debt claims of ₹20 lakh or more.
- Original Application (OA): The lender submits a formal claim detailing the default history and loan contracts.
- Recovery Order: After hearing both sides, the Presiding Officer issues an order fixing total liability.
- Recovery Certificate: The Recovery Officer issues a formal notice demanding clearance of dues within 15 days before exercising further statutory recovery powers.
Recovery Channel Outcomes: Practical Performance Data
Recovery rates differ sharply across legal avenues. Early outreach regularly yields better results than late court filings. How well each channel works depends heavily on loan type and collateral value.
Legal recovery avenues show contrasting efficiency in practice. Research published by Dataful on recovery channel performance[10] shows actual recovery sums across legal routes in FY 2024-25:
| Recovery Mechanism | Recovered Volume (FY 2024-25) | Recovery Rate / Performance Profile |
|---|---|---|
| Insolvency and Bankruptcy Code (IBC) | ₹54,528 crore | Roughly 36.6% recovery rate |
| SARFAESI Enforcement | ₹32,466 crore | Direct collateral sale for secured loans |
| Lok Adalats | ₹4,750 crore | Roughly 2.4% recovery rate across high case volumes |
Lok Adalats settle small claims quickly, yet their total recovery share stays low. Lenders weigh these differences when choosing between court channels and specialized debt collection management software.
What This Means for Collections and Recovery Teams
Read together, the recovery timelines and channel outcomes indicate that loan value decays quickly after the first month of arrears. The 80% recovery rate cited in early delinquency drops by half once loans reach NPA status. Court avenues like Lok Adalats return only 2.4% despite processing high case volumes.
This pattern indicates that daily outreach workflows and legal recovery paths serve distinct operational roles. Early digital contact recovers most overdue cash before mandatory loan-loss reserves tie up capital. By contrast, legal remedies like SARFAESI and Debt Recovery Tribunals act as enforcement tools against borrowers who refuse to pay.
The practical conclusion for BFSI teams is that early automated contact brings the highest cash return. Because lenders bear full legal liability for third-party agent conduct, enforcing call hour caps and recording lines protects banks from regulatory fines while speeding up cash recovery.
Frequently Asked Questions
This guide summarizes public Reserve Bank of India circulars, laws, and market reports for informational purposes. It is not legal, regulatory, tax, or compliance advice. Lenders should consult counsel for formal advice.
Bhanujeet Choudhary
Head of Compliance, KYCKART
Published August 19, 2026
KYCKART Intelligence
Bring Intelligence Directly to the Debt Collection Process
Equip your collections and risk teams with real-time borrower verification, proactive credit risk alerts, and compliant recovery tracking across every DPD bucket.
Explore Collections Intelligencearrow_forward